When Rumours Move Markets: Understanding SEBI’s New Rules for Listed Companies
Why Rumours Matter?
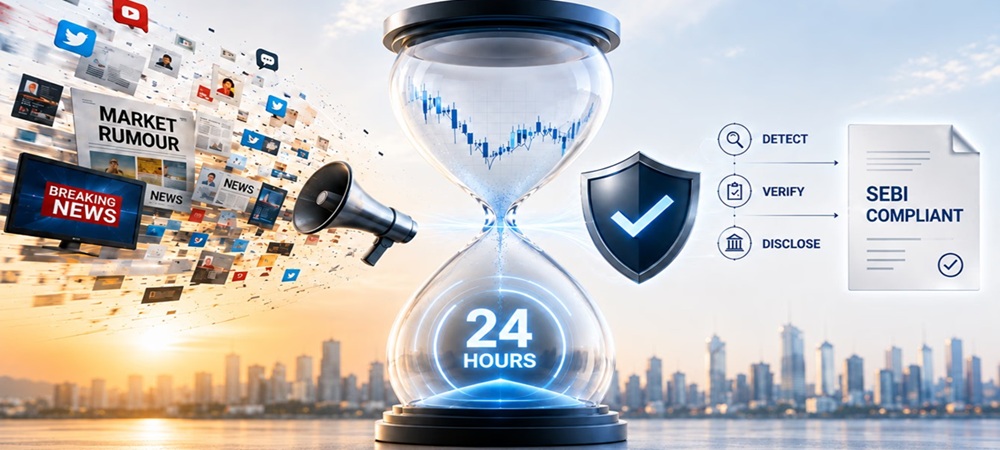
A report that a business has merged, acquired or invested in or sold another business can alter a company's share price even before the company officially merges, acquires, invests in or sells the business. Investors read the report then make a decision and take action. At times the report is correct but sometimes it's just early speculation. In either case, the price is up and down already however this lacuna is addressed by Securities and Exchange Board of India ("SEBI") to the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 ("LODR"). They imposed several conditions on certain listed large companies regarding the confirmation, denial or clarification of certain market rumours.
The Problem with M&A Rumours
The disclosure of material events is regulated in the SEBI (Listing Obligations and Disclosure Requirements) (Second Amendment) Regulations, 2023 notified on June 14, 2023 (“Amendment Regulations”). Within this framework are mergers, acquisitions and restructuring, as well as the sale of a business. The issue has been the same throughout, determining when a proposed transaction would become a final deal and be sufficiently material and definite to warrant disclosure. Typically, an M&A transaction will follow a sequence of steps. The parties enter into discussions and start to agree confidentiality agreements, make appointments of advisers, undertake due diligence and discuss commercial terms. At this point, the deal is not guaranteed to happen. It may fail due to the valuation, regulatory clearance, or due diligence findings, or disagreement on terms. If a company had to disclose every early conversation, genuine negotiations would become difficult to conduct. Another interesting example is that of Zomato and its acquisition of Blinkit. The investors of Zomato wrote a letter to SEBI complaining that there were market rumours and speculation of the acquisition of Blinkit by Zomato, however the absence of a timely confirmation or denial of such speculations by Zomato had led to the investors incurring losses, as they were unaware of the deal till it was announced much later on June 24, 2022. The investors were acting on information that was already available to investors, and the company had no "obligation" to act on that information. The regulation as it stood then provided that a listed company, on its own initiative, could confirm or deny an event reported. This provided companies with discretion, rather than a responsibility to answer. This gap has been filled with the current framework for a limited number of large companies.
How the Old Rule Worked and The Market Rumour Amendment
Before the amendment, LODR contained a general provision under which a listed entity could, suo moto, confirm or deny any reported event or information to the stock exchange. Following the amendment, two specific provisos were added to Regulation 30(11) , which provide as follows:
“Provided that the top 100 listed entities (with effect from October 1, 2023) and thereafter the top 250 listed entities (with effect from April 1, 2024) shall confirm, deny or clarify any reported event or information in the mainstream media which is not general in nature and which indicates that rumours of an impending specific material event or information in terms of the provisions of this regulation are circulating amongst the investing public, as soon as reasonably possible and not later than twenty four hours from the reporting of the event or information:
Provided further that if the listed entity confirms the reported event or information, it shall also provide the current stage of such event or information”.
Under the LODR, listed companies could choose to confirm or deny media reports if they wanted to, but nothing compelled them, which changed with the Amendment Regulations, which introduced the mandatory confirmation/clarification/denial of any reported event or information in the mainstream media by a listed company ("Market Rumour Amendment"). The Market Rumour Amendment now requires the top 100 and, eventually, top 250 listed entities to confirm, deny, or clarify any market-moving report within 24 hours, and to spell out the stage if they confirm it. SEBI had penalised Reliance and two of its compliance officers for sitting on disclosure of its confidentiality agreement and term sheet with Facebook even after credible media had already reported on the deal, and the Supreme Court upheld that ₹30 lakh penalty, dismissing Reliance’s appeal and making clear that bigger companies carry a bigger burden when it comes to responding to market rumours that could move their stock. The ruling makes it clear that staying silent on market-moving rumours is no longer a viable option, and the bigger and more closely watched a company gets, the stronger that obligation to speak up becomes.
When Does a Rumour Need a Response?
Whether a report requires general or specific information determines whether a response is needed or not. The statement that a company is planning acquisitions in the technology segment is general in nature. It can be said for any company at any time. The report describing the proposed transaction and specifying the target company and the parties to the transaction is specific. It gives investors something particular and certain to act on. A company may be considering multiple acquisition options, but have not yet made a decision on which to pursue. The Market Rumour Amendment targets information about a specific and impending material event, not every internal conversation a company happens to have. It doesn't apply to all statements and speculations about a company. Both of the following conditions must be satisfied which is the report must refer to a specific and imminent material event or piece of information and the price of the company's securities must exhibit the required price movement. If both of the above are satisfied, the company has 24 hours from the time the report is published to respond.
What Makes Information Specific?
Whether or not a report needs a response depends on the distinction between general and specific information. Any announcement by a company that it's looking to make some technology related acquisitions is a blanket statement. The report that contains identification of the target, description of the transaction and the parties is specific. It provides investors with a tangible basis to act on. This protection is for true business activity. A firm may be considering multiple acquisition options, none of which are binding at this point. This rule focuses on information related to a specific and imminent material event and not on all the internal conversations a company may be having.
What Counts as Mainstream Media?
The obligation also depends on where the report appears. For this purpose, mainstream media does not mean limited to established newspapers and TV networks. It comprises newspapers registered under the Registrar of Newspapers for India, news channels allowed by the Ministry of Information and Broadcasting, Digital news content under the Information Technology Rules and relevant news content outside India. This broader definition is important because the information about listed companies flows quickly through online publications than in traditional media. A digital report can impact the trading within hours and companies must monitor it. The members of the Industry Standards Forum (ISF) of SEBI, who are from the ASSOCHAM, CII, FICCI, met with the stock exchanges and developed ‘practical standards' for verifying market rumours. In May 2024, SEBI has issued the Industry Standards on Verification of Market Rumours.
The YES Bank Rumour: Did the Clarification Tell the Whole Story?
YES Bank had disclosed SMBC’s proposed 20% stake acquisition on May 9, 2025. When reports emerged on June 2 suggesting that SMBC was considering a controlling stake and discussions with the RBI, YES Bank responded on June 3, stating that it was not privy to the reported discussions and that the reported RBI “road map” was factually incorrect. The issue is not the 20% transaction, which was already disclosed, but whether the clarification correctly answered SMBC’s wider involvement and the discussions behind the report. The Market Rumour Amendment requires companies to give investors a clear position on material rumours, not simply issue a denial.
How Companies Should Respond?
A response must address the content of the report directly. A generic line about regularly evaluating business opportunities does not meet the requirement once a report is specific enough to trigger the obligation. The company must respond to the content of the report, and if it admits the deal, it must disclose the progress of the transaction.
Keeping M&A Talks Confidential
The rumour verification requirement does not require companies to provide full disclosure of the stage of an M&A discussion. Confidentiality is still important in negotiations. Parties exchange sensitive details about valuation, financing, commercial terms, due diligence and regulatory approval. It could impact the negotiation itself if it's revealed too soon, and give competitors valuable information. The question is whether the information has advanced beyond a business conversation to "a material event" that's likely to impact the business in the near future. The closer a transaction gets to a definite stage, the more important an accurate response becomes if a specific report about it reaches the market. The Reliance dispute falls right in the middle of this band, as information around the Facebook-Jio deal was being shared, but the deal itself was still in the process of being negotiated.
Wording Cannot Be Careless About What the Company Knew
The company's response should be based on what it knew at the time of the statement. If an announcement occurs later it does not necessarily imply that an earlier clarification was incorrect. The key is what information is present for the company at the time. There is a real difference between saying a company has no information about a reported transaction and saying discussions are at a preliminary stage, and issuing a flat denial that any discussions exist. Each of these carries a different meaning, and each has different consequences if the transaction later goes ahead. A company therefore has to be precise about the language it uses in a stock exchange filing. A knowingly false statement flags a separate concern under the SEBI’s Prohibition of Fraudulent and Unfair Trade Practices (“PFUTP Amendment Regulations”) which covers knowingly publishing, or causing to be published, information about securities that is untrue or that the person does not believe to be true. A rumour clarification is not a public relations exercise. It is an official disclosure, and it has to be treated as one.
Consequences of a False Statement
Things get more serious when a statement is not just wrong but knowingly false and that falls under the PFUTP Amendment Regulations which is not written only for rumour clarifications, but it applies to a company that uses a false denial to mislead the market on purpose. This is the line that separates a clarification that turns out to be wrong in hindsight from one that invites regulatory trouble.
How Rumours Affect Share Prices?
A market rumour does more than create confusion. It can move the actual price of a company's shares, and that matters because several SEBI regulations use market price to determine the price of a transaction, such as a preferential issue or an open offer. A rumour about an acquisition can push the target company's share price up before anything is officially announced. If that inflated price is then used to calculate the transaction price, the acquirer ends up paying more, purely because of information that entered the market too early.
Understanding the Unaffected Price
To deal with this, SEBI introduced the concept of an unaffected price. The idea is to strip out the effect of the rumour, and its later confirmation, from the price used in the transaction calculation. A 60-day protection period applies where an identified counterparty is involved and the transaction is at an advanced stage. This extends to 180 days in a competitive bidding situation, where no exclusive bidder has yet been identified. The mechanism also applies to buy-backs. Under Regulations 19 and 22B of the SEBI (Buy-Back of Securities) (Amendment) Regulations, 2024 , the effect of a rumour and its confirmation can be excluded when determining the volume weighted average market price and the lower end of the buy-back price range, respectively. This prevents rumour-driven price movements from distorting the buy-back price. The Zomato-Blinkit case shows why the timing of information matters in the first place. The unaffected price mechanism deals with what happens once that information has already moved the market price.
What Companies Need to Do?
The Market Rumour Amendment has added real, practical compliance work for large listed companies. Companies covered by it have to monitor newspapers, television channels and digital news sources, and identify reports that concern a specific material event. Once such a report appears, the company has to check whether it meets the two conditions: whether the event is specific and impending, and whether the required price movement has taken place. It then has to gather information from the relevant people inside the company and prepare an accurate response within the prescribed period. This requires coordination between the company secretary, the legal and compliance teams, senior management and, in M&A matters, external advisers. Promoters, directors and key managerial personnel are expected to give the company accurate and timely information whenever verification is required because reports can appear anywhere and spread quickly, internal confidentiality controls matter more now too. A company cannot control what gets published, but it can control how sensitive information moves internally and how fast the right people respond once a report surfaces.
Conclusion
The Market Rumour Amendment has changed how large listed companies deal with market rumours. The LODR left the choice to respond with the company. The current framework creates a specific obligation once the prescribed conditions are met. The rule does not require companies to disclose every early-stage discussion. It is aimed at information that is specific, material and close to happening. This distinction protects genuine M&A negotiations, which depend on confidentiality and often change shape before anything is finalised. The unaffected price mechanism addresses the other half of the problem, by preventing a price movement caused by a rumour from becoming the basis for pricing a transaction. For listed companies, the practical position is now straightforward. Relevant media reports have to be tracked, information has to be checked internally, and an accurate response has to go out within the prescribed time. The change is not only about making companies talk more. It is about marking the point at which information in the market becomes specific, material and imminent enough to require an official response.
-Authored by Anamika Singh, under the guidance of Mallika Agrawal, Associate.
Disclaimer
This publication has been prepared by RMA Legal for general informational purposes only and does not constitute legal, tax, financial or any other professional advice. The information has been compiled from sources believed to be credible; however, it is provided on an “as is” basis without any representation or warranty, express or implied, as to its accuracy or completeness, and RMA Legal shall not be liable for any loss arising from reliance on this publication. Readers are advised to seek appropriate professional advice before taking any action.
We Provide Legal Solutions to Grow your Business
RMA Legal (RMA) is established by a team of dedicated professionals coming from varied streams of law. The foundations of RMA are knowledge, faith, integrity and trust.